Case Summary: Marelli Automotive Chapter 11
Marelli, the Japan-headquartered automotive supplier, filed chapter 11 in Delaware on 11 June 2025 with approximately $4.9bn of funded debt after eight months of failed out-of-court talks in which neither of two lender camps could reach the 66.67% supermajority the Japanese-law credit agreement requires to act. The case has since produced a plan that pays the Japanese banks 11 cents on the dollar in cash, hands the DIP lenders 100% of the reorganized equity and leaves general unsecured creditors, many of them Marelli's own customers, unimpaired.
Case details
- Court
- US Bankruptcy Court, District of Delaware
- Case number
- 25-11034 (CTG), jointly administered
- Judge
- Craig T. Goldblatt
- Petition date
- 11 June 2025
- Debtors
- Marelli Automotive Lighting USA LLC and 75 affiliated debtors
- Funded debt
- Approximately $4.9bn
Marelli, the Japan-headquartered automotive supplier behind brands most drivers have never heard of and vehicles they sit in every day, filed chapter 11 in Delaware on 11 June 2025 with approximately $4.9bn of funded debt. The filing ended eight months of failed out-of-court talks in which neither of two lender camps, Japanese commercial banks holding roughly half of a ~$4.55bn senior facility and an ad hoc group of largely non-Japanese investors holding the other half, could reach the 66.67% supermajority the Japanese-law credit agreement requires to act. Sixteen months later the case has produced a plan that does something the prepetition negotiation never could: pay the Japanese banks 11 cents on the dollar in cash, hand the DIP lenders 100% of the reorganized equity, and leave general unsecured creditors, many of them Marelli's own customers, unimpaired. Judge Craig T. Goldblatt approved the disclosure statement on 20 October 2026, sending the plan out to a creditor vote with a deadline of 23 November 2026 and a confirmation hearing set for 8 December. The creditors' committee's challenge period against the prepetition lenders runs to 23 October, and the plan's feasibility still rests on accommodation agreements with Marelli's largest customers that had not been signed as of the amended disclosure statement.
Business description
Marelli Holdings Co. Ltd. is a global automotive supplier headquartered in Saitama, Japan, with its North American headquarters at 26555 Northwestern Highway in Southfield, Michigan. The company reported $10bn of revenue for 2024, employed more than 46,000 people across 24 countries at the petition date, and served more than 65 original equipment manufacturers (Dkt 20, ¶¶ 21 to 24). Marelli organizes production into seven businesses: Lighting, Electronics, Interiors, Ride Dynamics, Propulsion, Green Technologies and Aftermarket.
Corporate history
KKR buys Calsonic Kansei, 2016 to 2017. Kohlberg Kravis Roberts announced a tender offer for Calsonic Kansei, the Nissan-affiliated supplier, on 22 November 2016 and completed it on 23 March 2017, with 95.21% of shares tendered. The Nissan-Renault-Mitsubishi Alliance was CK Holdings' primary customer at the time.
Magneti Marelli, 2018 to 2019. KKR agreed in October 2018 to buy Magneti Marelli from FCA for €5.8bn ($6.66bn) and closed in 2019. The two businesses were merged to form Marelli Holdings, a group Corriere della Sera put at more than $10bn of revenue.
The 2022 Japanese turnaround. Marelli ran a first restructuring out of court in Japan in 2022, cutting roughly ¥450bn from ¥1.1tn of debt with ¥650m of new capital from KKR and a ¥200bn write-off. The 2025 chapter 11 is its second restructuring in three years.
Industry precedent transactions
The Marelli filing lands inside a broader supplier squeeze. 9fin's August 2025 survey of the sector, "OEMs take the wheel in supplier restructurings", documents automakers pressing suppliers on price and payment terms, OEMs absorbing tariff costs selectively, and a run of supplier insolvencies across Europe and North America. Marelli is the largest supplier restructuring of the cycle, and the only one so far in which the lenders rather than the sponsor end up owning the company.
Operations overview
Lighting is the largest business: nineteen production plants in eleven countries, sixteen R&D and application centers, and approximately 16,100 employees, selling lighting and electrical systems predominantly to European and North American automakers. Electronics, the second largest, employs approximately 5,800 people across eleven manufacturing sites in ten countries, with strategic investments in China and India and a product line migrating toward software-defined-vehicle architecture. Interiors operates twenty-five manufacturing sites in eight countries with approximately 6,000 employees and holds more than seventy patents, including the first smart-surface technology launched by a Tier 1 supplier (Dkt 20, ¶¶ 26 to 30).
The remaining businesses: Ride Dynamics, approximately 3,700 employees across twelve plants in six countries, making powertrain-agnostic suspension and shock absorbers; Propulsion, approximately 3,800 employees across seven plants in seven countries, supplying combustion-engine components and electric "engines", with motorsport collaborations including McLaren and Ferrari; Green Technologies, more than 6,700 employees across thirty-one plants in fourteen countries, the emissions-products arm; and Marelli Aftermarket, which distributed approximately 80,000 spare parts to more than 3,000 customers in over ninety countries in 2024 under the Magneti Marelli Parts & Services brand. The amended disclosure statement's financial projections, dated 16 October 2026, assume continued operation of eight key segments, adding Motorsport, with partnerships including the Nissan Formula E team and Ducati Corse's MotoGP program. Marelli does not disclose revenue by segment, so the workforce and plant counts above are the only public measure of relative business size.
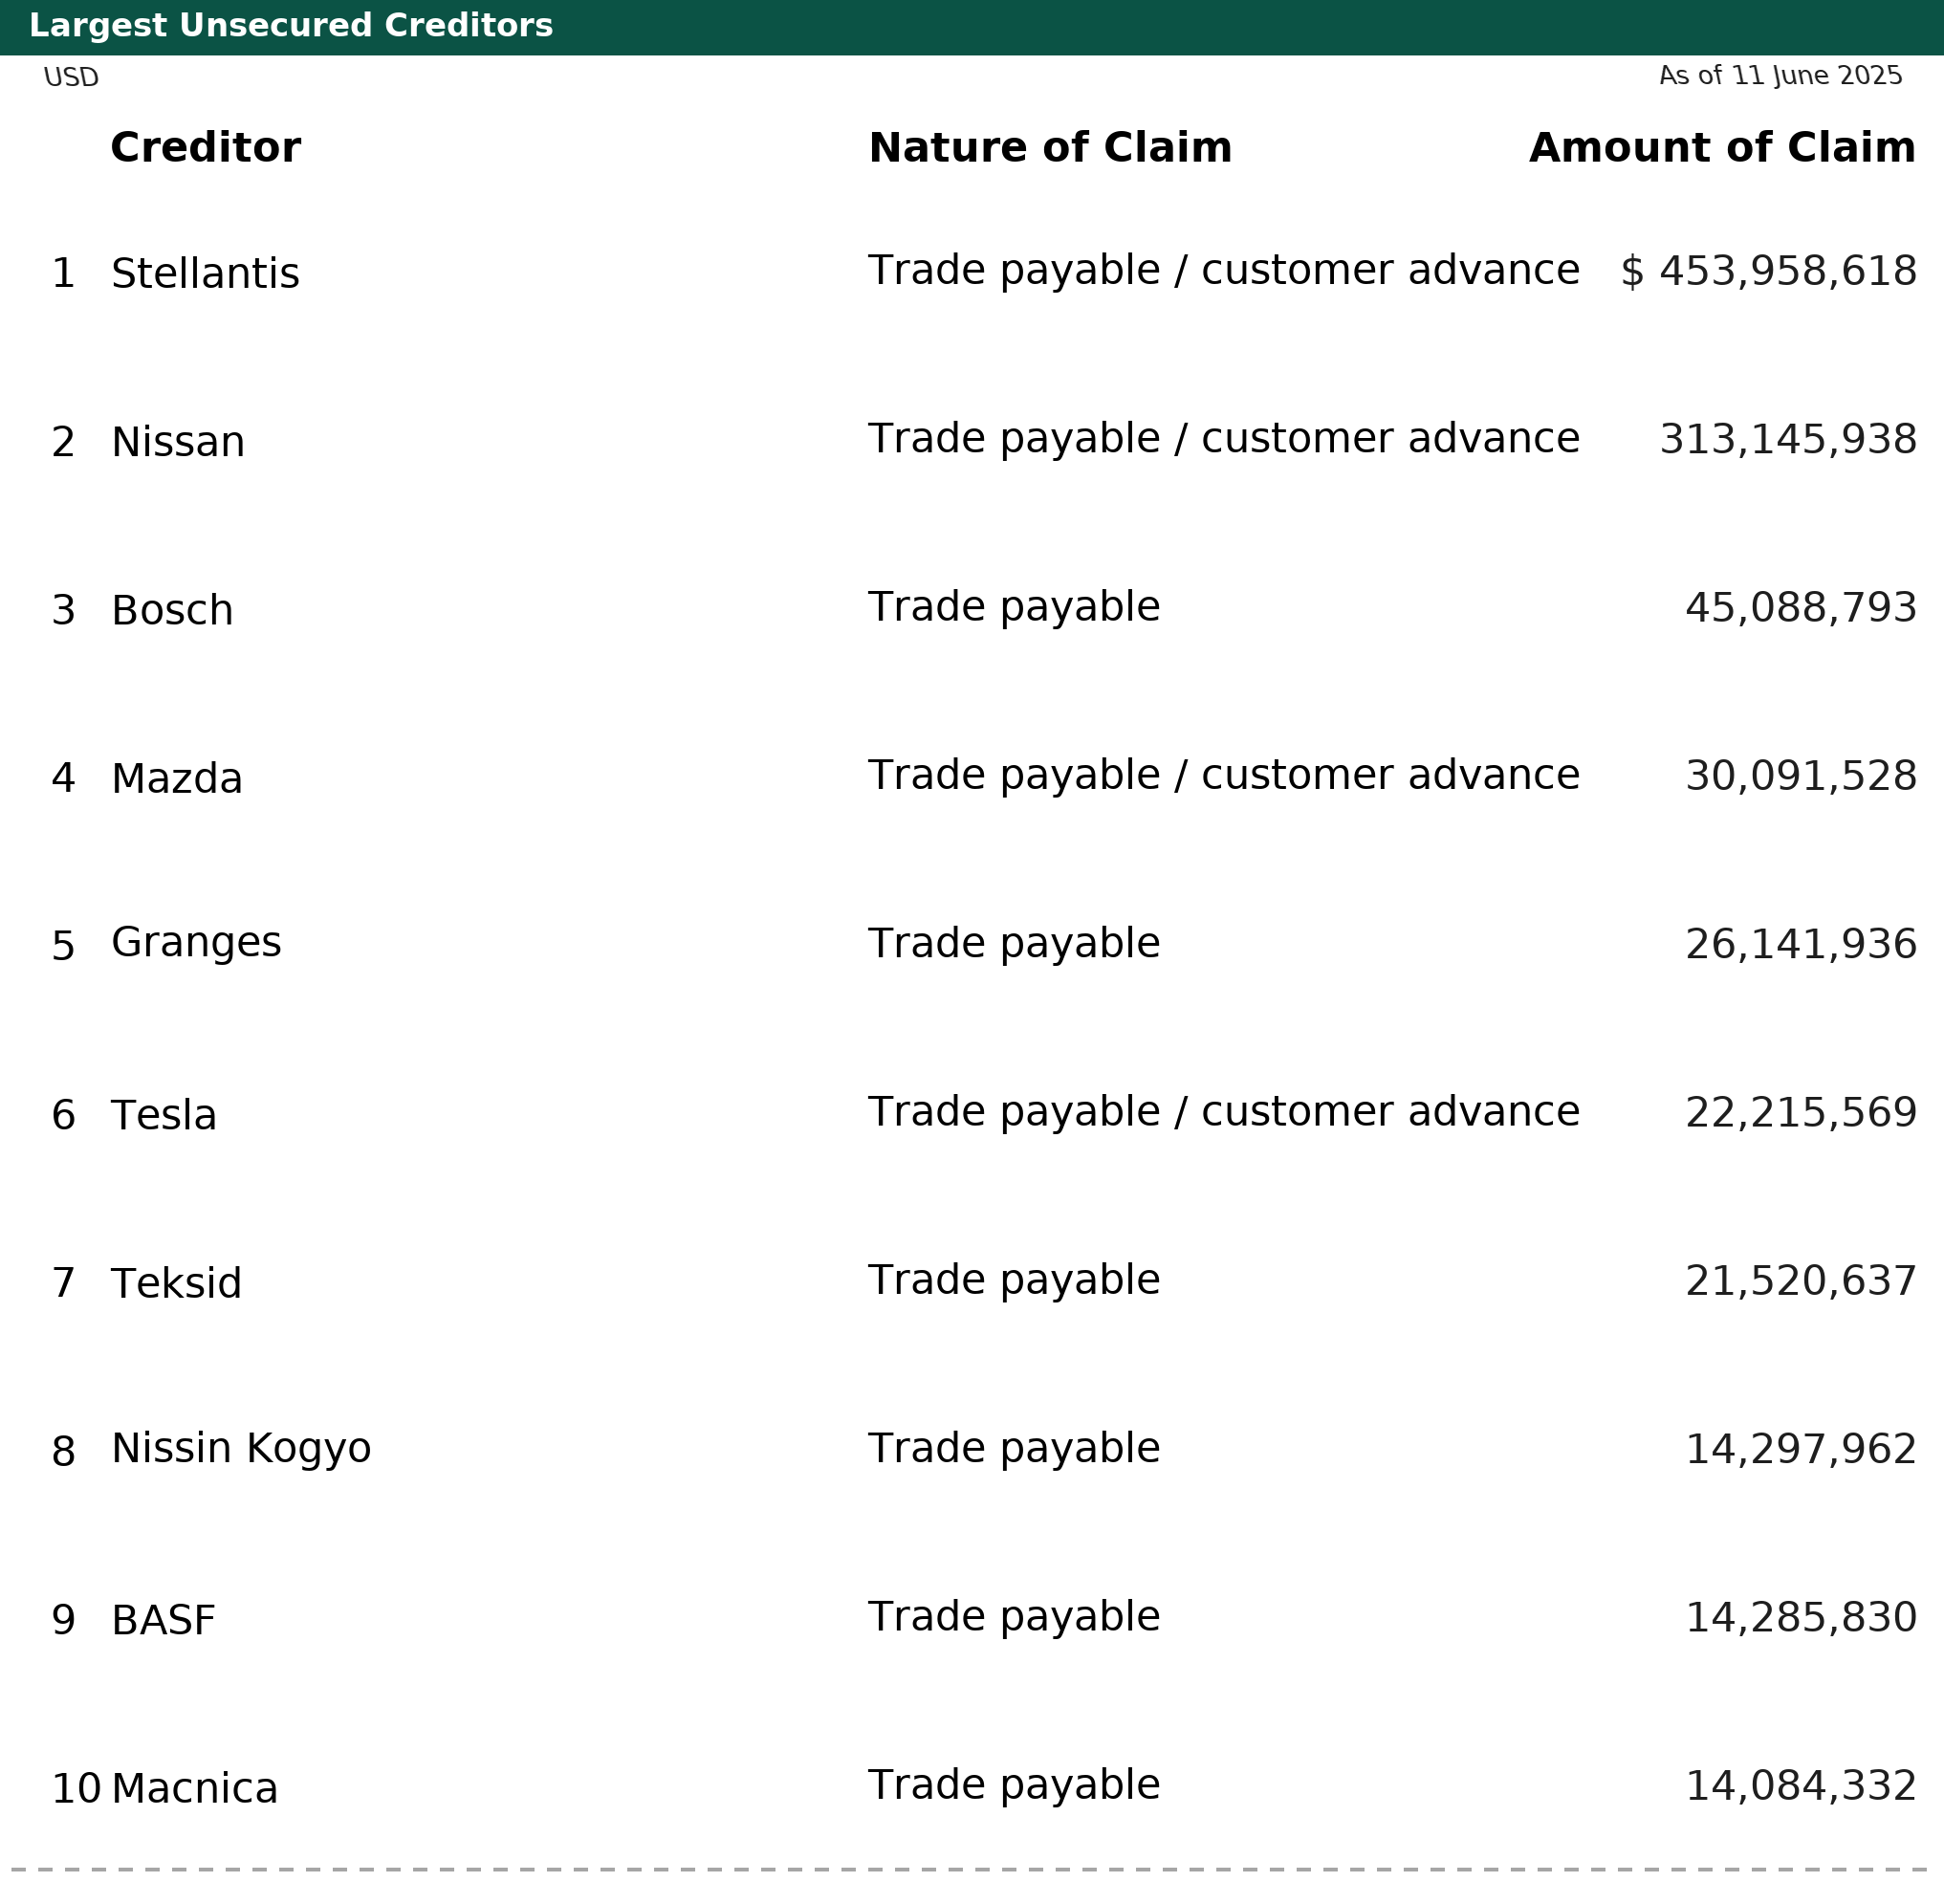
Customers concentrate in exactly the way the plan's critics point to. Stellantis is simultaneously Marelli's largest global customer and, at $453,958,618, its largest non-bank creditor. Nissan is second at $313,145,938 and has been the subject of its own closely watched turnaround. The company spent more than $750m supporting customers in 2024 and 2025 (Dkt 20).
Top unsecured claims
The thirty largest unsecured creditors are consolidated on a single list attached to the lead debtor's voluntary petition. The ten largest:
Source: Verita Global, court filings.
The list is unusual in a chapter 11 of this size: the two largest claims are customers, not lenders or bondholders, and both sit outside the restructuring's secured classes entirely. Pension-related entries (PBGC and the Dutch pension fund PPF) appear on the Form 204 list as contingent and unliquidated claims rather than dollar-quantified amounts.
Events leading to bankruptcy
Financial deterioration. Marelli began engaging its secured lenders in August 2024 to address liquidity needs and potential credit-agreement amendments, retaining Kirkland & Ellis, Nishimura & Asahi and Mori Hamada & Matsumoto as counsel, PJT Partners as investment banker and Alvarez & Marsal as financial advisor (Dkt 2852). A J.P. Morgan-led 2024 financing effort produced no actionable proposals. The senior facility's Japanese-law terms require at least 66.67% of lenders by principal amount to direct remedies, and with roughly half held by Japanese banks and half by the ad hoc group, each side ended the talks holding approximately 50%, enough to block and not enough to act. Eight months of negotiation deadlocked. Tariffs imposed in March 2025 worsened the liquidity position of a company whose business model moves components across borders in both directions. Annual interest on the funded debt ran to approximately $150m.
Nikkei-reported Motherson approach. In May 2025, Nikkei reported a buyout proposal from India-listed supplier Motherson. It could not bridge the gap between Japanese and non-Japanese creditor groups in time, and the case went to court instead.
Litigation. OPmobility Gestion et al. v. Strategic Value Partners LLC, Marelli Holdings Co. Ltd. et al., Adv. Pro. No. 26-50470-CTG (Bankr. D. Del.), filed 16 June 2026. OPmobility alleges the debtors and SVP are attempting to hire its former chief executive, Laurent Favre, while he remains subject to a non-compete agreement, and pleads related trade-secret claims. The defendants moved to dismiss the first amended complaint under Rule 12(b)(6) on 11 September 2026 and to dismiss on forum non conveniens grounds on 18 September 2026 (Dkt 2852). The adversary is ongoing.
Independent investigation. At the direction of a special committee, Selendy Gay has conducted an independent investigation of potential claims against related parties arising from prepetition transactions, including document requests to KKR and access to a data room maintained for lender groups (Dkt 2852). The investigation remained ongoing as of the amended disclosure statement.
State investigations. None are disclosed in the amended disclosure statement.
Federal and foreign regulatory matters. The disclosure statement identifies no regulatory approvals as required to consummate the plan beyond standard conditions. On 29 June 2026 the Delaware court entered a Merger Order approving, on an expedited basis, the merger of Marelli Sophie Antipolis France and Marelli Smart Me Up into Marelli France, a corporate simplification inside the cases rather than a matter for a French regulator. The debtors note that parts of the restructuring must be effectuated on an expedited timeline to satisfy Italian regulatory requirements.
The chapter 11 filing
Marelli Automotive Lighting USA LLC and 75 affiliated debtors filed voluntary chapter 11 petitions in the District of Delaware on 11 June 2025. First-day relief included cash management, customer and vendor programs, and approval of the initial DIP draw. The court approved an interim draw of $519m under the senior DIP facility on 12 June 2025, a second interim draw of $130m on 25 July 2025, and final DIP approval on 30 July 2025. The $350m Emergency Loan Facility was repaid in full in cash at final DIP approval. An official committee of unsecured creditors was appointed on 25 June 2025, with Paul Hastings as counsel.
The capital structure entering the case: a $350m Emergency Loan Facility, contractually senior, with DBJ as lender and Mizuho as agent, maturing 31 December 2027; and a ~$4.55bn Senior Loan Facility under Japanese law, comprising a $540m revolving facility and a $4,010m term loan, first-lien. Roughly half of the senior facility is held by Japanese commercial banks, with Mizuho as administrative agent, and roughly half by the ad hoc group, which includes investors based outside Japan. KKR funds hold the equity.
Restructuring support agreement
Marelli signed a restructuring support agreement with holders of approximately 80% of the senior loan claims, the ad hoc group, Mizuho and KKR before filing. Its key terms (Dkt 2852):
New-money priming DIP. Up to approximately $1.1bn of new-money priming DIP financing, funded by Deutsche Bank AG, London Branch, certain other new money lenders, and members of the ad hoc group.
Roll-up. A roll-up of 47.5% of the senior loan claims held by DIP lenders, effective on entry of the final DIP order. The rolled claims become "last out" DIP loans denominated in euro and yen.
Emergency loan repayment. Repayment in full in cash of the approximately $350m Emergency Loan Facility.
Japanese lender cash-out. An 11% cash recovery on the senior loan claims held by the Japanese lenders, on plan consummation.
General unsecured creditors. Reinstatement or payment in full in cash of all general unsecured claims.
Equity. Conversion of a portion of the DIP facilities into 100% of the reorganized common equity on plan consummation.
DIP financing
The initial DIP facilities totaled approximately $1.1bn: a first-out super-senior senior DIP facility of up to approximately $865m of new-money term loans available in three draws ($519m, $130m and the balance), and a second-out junior DIP facility of up to approximately $242m of new money, plus the 47.5% roll-up. In June 2026 the facilities were amended (Dkt 2218) to provide approximately $300m of incremental liquidity: the Tranche A facility increased from approximately $865m to $900m, and a new Tranche A-1 senior facility of up to $300m was added, ranking ahead of the Tranche B loans and taking the junior DIP from approximately $242m to up to $542m. Maturities were extended to 31 December 2026, with automatic extension to 31 March 2027 on satisfaction of conditions. The debtors submitted a borrowing notice on 23 July 2026 drawing the remaining Tranche A-1 loans on 7 August 2026, at which point the DIP facilities stood fully drawn. The DIP carries milestones that mirror the restructuring support agreement's; missing one is an event of default. Alongside the DIP, the debtors negotiated a new $215m uncommitted accounts receivable purchase facility with Deutsche Bank's New York branch.
OEM accommodation agreements
The plan's feasibility clause is its customer list. The amended disclosure statement states that negotiations with individual OEMs remain ongoing, that the debtors have made substantial progress toward post-emergence contractual arrangements, and that the financial projections assume OEM support in the form of pricing adjustments, lump-sum payments, accelerated or modified payment terms, volume and sourcing commitments, and recovery of tooling, engineering and capital expenditures, with no assurance that any of it is agreed (Dkt 2852). The plan's effectiveness conditions require OEM accommodation agreements in form and substance acceptable to the debtors and the required plan sponsors, approved by the court.
Two customers have put their positions on the docket. FCA US LLC filed a limited objection on 1 September 2026 (Dkt 2581): Stellantis is the debtors' largest global customer and largest non-bank creditor, plan feasibility depends entirely on customer accommodation agreements, and as of filing no mutually acceptable agreement with Stellantis had been reached. FCA supported disclosure statement approval while reserving rights on amendments and confirmation. BMW Manufacturing filed a reservation of rights the same day (Dkt 2583): it is a proposed accommodation party with no agreement reached, its executory contracts are neither assumed nor rejected, and it reserves rights on cure, assumption and assignment and plan objections.
Where the plan stands
The joint plan and disclosure statement were filed on 3 August 2026 (Dkt 2510, 2511). The disclosure statement hearing, originally set for 8 September 2026, was adjourned to 20 October 2026 at 1:00pm ET before Judge Goldblatt, who approved the disclosure statement and solicitation procedures that day (Dkt 2870). The debtors filed an amended plan and amended disclosure statement on 16 October 2026 (Dkt 2851, 2852); objections to the disclosure statement had been due 8 October 2026. The committee supported the move to solicitation, objecting to neither the level of disclosure nor the solicitation procedures (Dkt 2853), while flagging the plan's contingencies: general unsecured treatment sits at the debtors' option with sponsor consent, effectiveness is conditioned on an exit facility acceptable to the sponsors, and the sponsors hold consent rights over the effective date debtor by debtor and over the aggregate amount of claims filed. It reserved its challenges to the prepetition secured claims if the plan is modified to impair the unsecureds or an alternative plan emerges. The order sets the confirmation timeline: solicitation packages mail by 26 October 2026, the plan supplement is due 16 November, voting closes and plan objections are due 23 November 2026 at 4:00pm ET, the voting report and confirmation briefs are due 3 December, and the confirmation hearing is set for 8 December 2026 at 10:00am ET. The creditors' committee's challenge period against the prepetition lenders, originally set to run until entry of the disclosure statement order, was extended by consent to 23 October 2026 (Dkt 2839), counsel for the committee being Pachulski Stang and Kirkland. Evidence closed on 15 October 2026.
The plan's economics (Dkt 2851): Class 3, the $308m Emergency Loan Facility, is paid 100% in cash. Class 4, $3,431m of senior loan claims, is impaired and votes: non-participating lenders receive cash equal to 11% of the sum of principal, accrued and unpaid interest, and fees through the day before the petition date, and participating lenders waive any recovery on their senior claims, including any deficiency. The participating lenders' recovery instead comes through the DIP: on confirmation, the plan sponsors' Tranche B and Tranche C DIP claims are equitized, converting into pro rata shares of the new common stock, subject to dilution by a management incentive plan whose terms the new board sets. Tranche A and Tranche A-1 DIP loans are paid in full in cash; Tranche B may instead be paid in cash or exchanged into exit facility loans at the sponsors' election. Upon equitization the sponsors waive recovery on their non-rolled-up senior loan claims. Class 5, $78m of general unsecured claims, is unimpaired and deemed to accept, reinstated or paid at the debtors' option with sponsor consent. Preferred equity, common equity and section 510(b) claims are cancelled with no recovery.
The debtors' best-interest test puts the alternative on the record: in the mid case, a chapter 7 liquidation returns 9.7% on the Emergency Loan Facility, 2.3% on other priority claims, and nothing to the senior lenders or the general unsecured creditors. The plan pays the emergency loans and the unsecureds in full and the senior lenders 11% (Dkt 2852-6).
What to watch. Voting on the plan, which closes 23 November 2026, and the confirmation hearing on 8 December. The challenge period expiring 23 October. Whether accommodation agreements with Stellantis, BMW and the other major OEMs are signed before confirmation, since the plan conditions its effectiveness on them and FCA's objection says none existed as of 1 September. The exit facility, which the plan requires to be executed and closed on the effective date.
Follow @EURestructuring for coverage of European restructurings from filing to plan confirmation, and subscribe at eurx.substack.com to receive each case summary.