Case Summaries · France
Casino cut €6bn of debt in 2024. Two years on, its TLB lenders are suing to unwind the plan
The 2024 safeguard equitized €4.9bn of debt and left a €1.4bn TLB behind. Two years on, its lenders are in the Paris courts to unwind the plan.

Key terms
- Company
- Casino Guichard-Perrachon, the French convenience retailer behind Monoprix, Franprix, the Casino, Spar and Vival banners, Naturalia and Cdiscount. Net sales of €8.26bn in 2025, 7,447 convenience stores at the end of 2024 plus Cdiscount
- 2024 process
- accelerated safeguard at the Paris commercial court, opened 25 October 2023 for Casino and six subsidiaries (including Monoprix, Quatrim and Ségisor). Plans approved 26 February 2024, implemented 27 March 2024. Recognised in the US through a chapter 15 case in the Southern District of New York (No. 24-10252, filed 15 February 2024), which closed in June 2024
- The 2024 deal
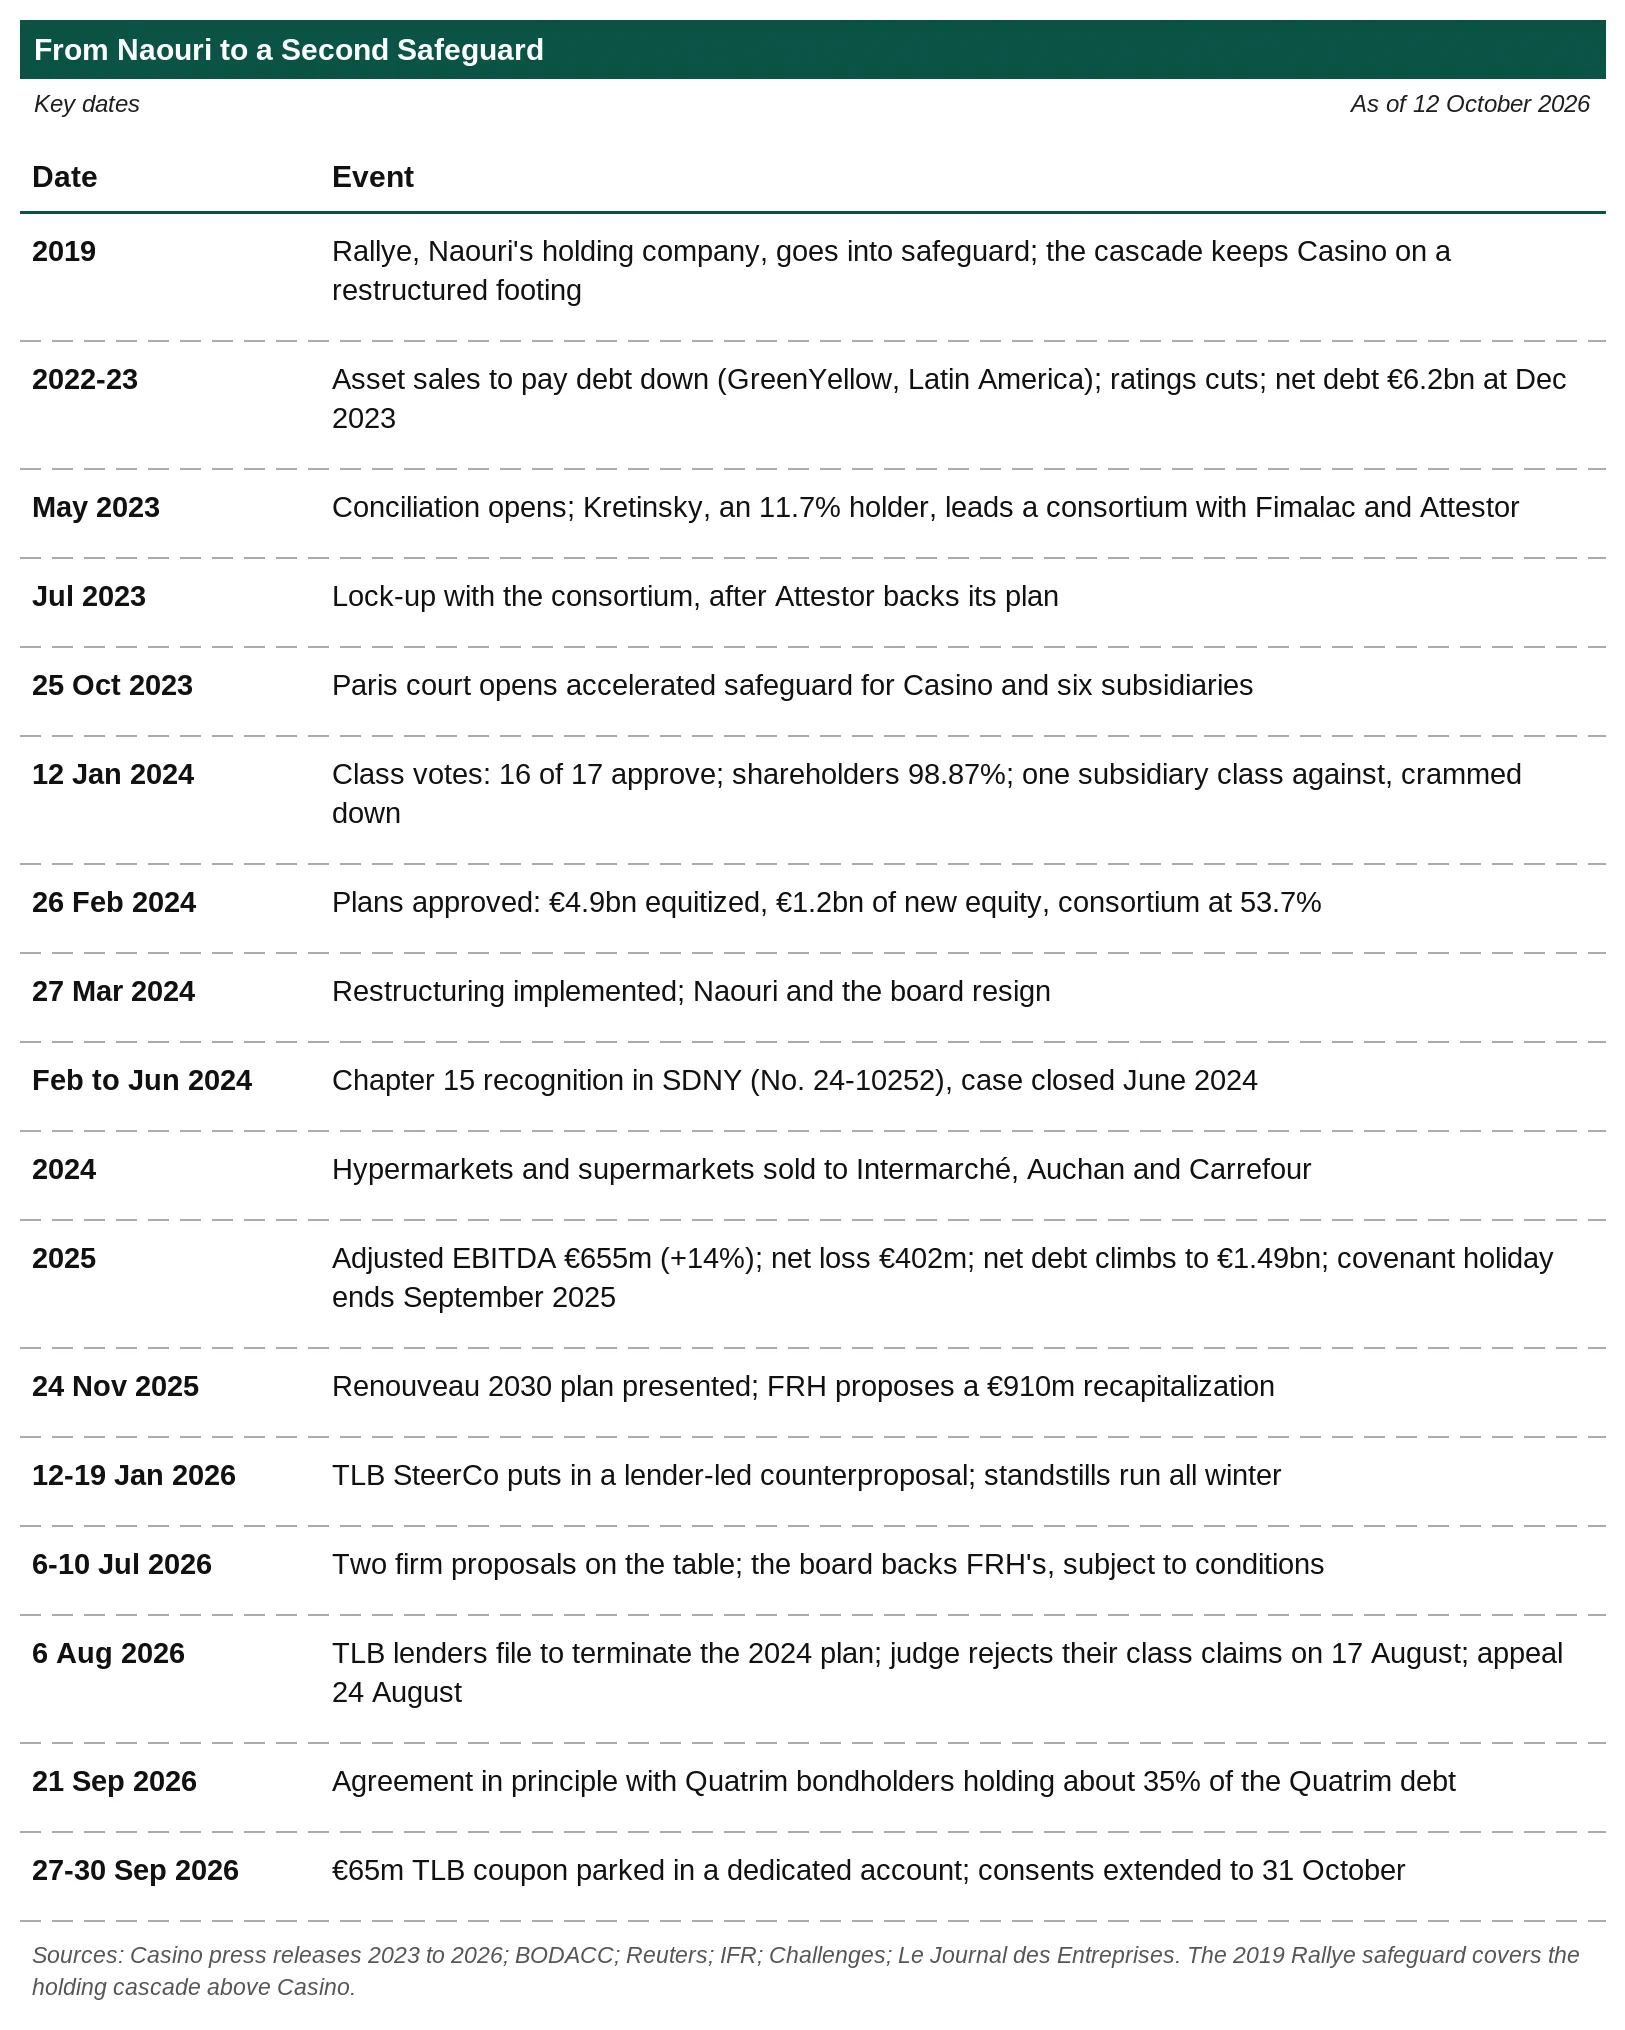
- €4.9bn of debt equitized (€5.2bn of principal and interest on the final tally, €3.8bn excluding TSSDIs), plus €1.2bn of new equity, of which €925m reserved to the Kretinsky consortium at €0.0435 a share. The consortium (France Retail Holdings) took 53.7%; existing shareholders went to about 0.3% in total
- What stayed outstanding
- €2.6bn of reinstated debt: the €1.4bn TLB due March 2027, the Monoprix RCF, and the ring-fenced Quatrim real estate bonds (€109m nominal today)
- 2026 process
- a second restructuring, run as an amendment of the 2024 safeguard plans. Two rival proposals, the Kretinsky vehicle FRH against a TLB lender group. The board backed FRH's on 10 July 2026; the TLB lenders refused consent and filed on 6 August 2026 to terminate the 2024 plan. A judge rejected their first claims on 17 August; they appealed on 24 August. Casino skipped the €65m TLB coupon due 27 September, parking it in a dedicated account, and on 13 October extended the Quatrim bonds' maturity from 15 January 2027 to 15 January 2028
- H1 2026
- net sales €4.0bn, adjusted EBITDA €326m (+13.9%), net loss €205m, net debt €1.7bn, liquidity €713m. The covenant sits at 6.47x against a 6.88x limit, and the group expects to breach the 6.11x step-down at end-September and will ask for waivers
How we got here: Naouri's acquisition spree ran out of road
The architect of the modern Casino group was Jean-Charles Naouri (JCN). Born in Algeria in 1949, he took first prizes at France's national concours général at 14 (in Latin and Greek), passed the baccalauréat at 15 with highest honours and in 1967 ranked first in France in the mathematics entrance examination to the École normale supérieure. After school, he joined the Finance Ministry and served as chief of staff to Pierre Bérégovoy, the French finance minister of the late 1980s and early 1990s who went on to be prime minister, then left for Rothschild in 1987 and set up Euris, his own investment vehicle. In 1991 Euris bought control of Rallye, a heavily indebted supermarket and hypermarket retailer based in Brittany. In 1992 Rallye brought its distribution and restaurant activities into Casino in exchange for shares that left JCN, through Rallye, the largest shareholder of the enlarged group. A hostile takeover bid from Promodès failed in 1997 against the counteroffer from JCN, the Guichard family and Casino management. JCN became chairman and chief executive in March 2005. Under his control Casino spent the next two decades acquiring retailers: a majority of Franprix and Leader Price in 1997, half of Monoprix and Cdiscount in 2000, the whole of Monoprix in 2013, and a growing footprint across Latin America and Asia. The purchase debt was issued at Casino; the holding debt above it was issued at Rallye and its own parents, secured on the Casino shares themselves.
Outside France, Casino built its largest business in Latin America. It bought into GPA in Brazil and Grupo Éxito in Colombia in 1999, strengthened both positions in 2005, and took control of GPA, Brazil's largest food retailer, in mid-2012, adding Big C in Thailand and Vietnam along the way. By 2018 Brazil alone was about 31% of Casino's revenues and 39% of its EBITDA.
Performance declined in the 2010s. Casino's stores, concentrated in city-centre convenience formats, began losing share, falling from ~11% to under 6% in the five years to 2023. From 2014 the group sold assets to reduce debt, hypermarkets among them: Thailand in 2016, Via Varejo in 2019, then GreenYellow, Éxito and the rest of Brazil.
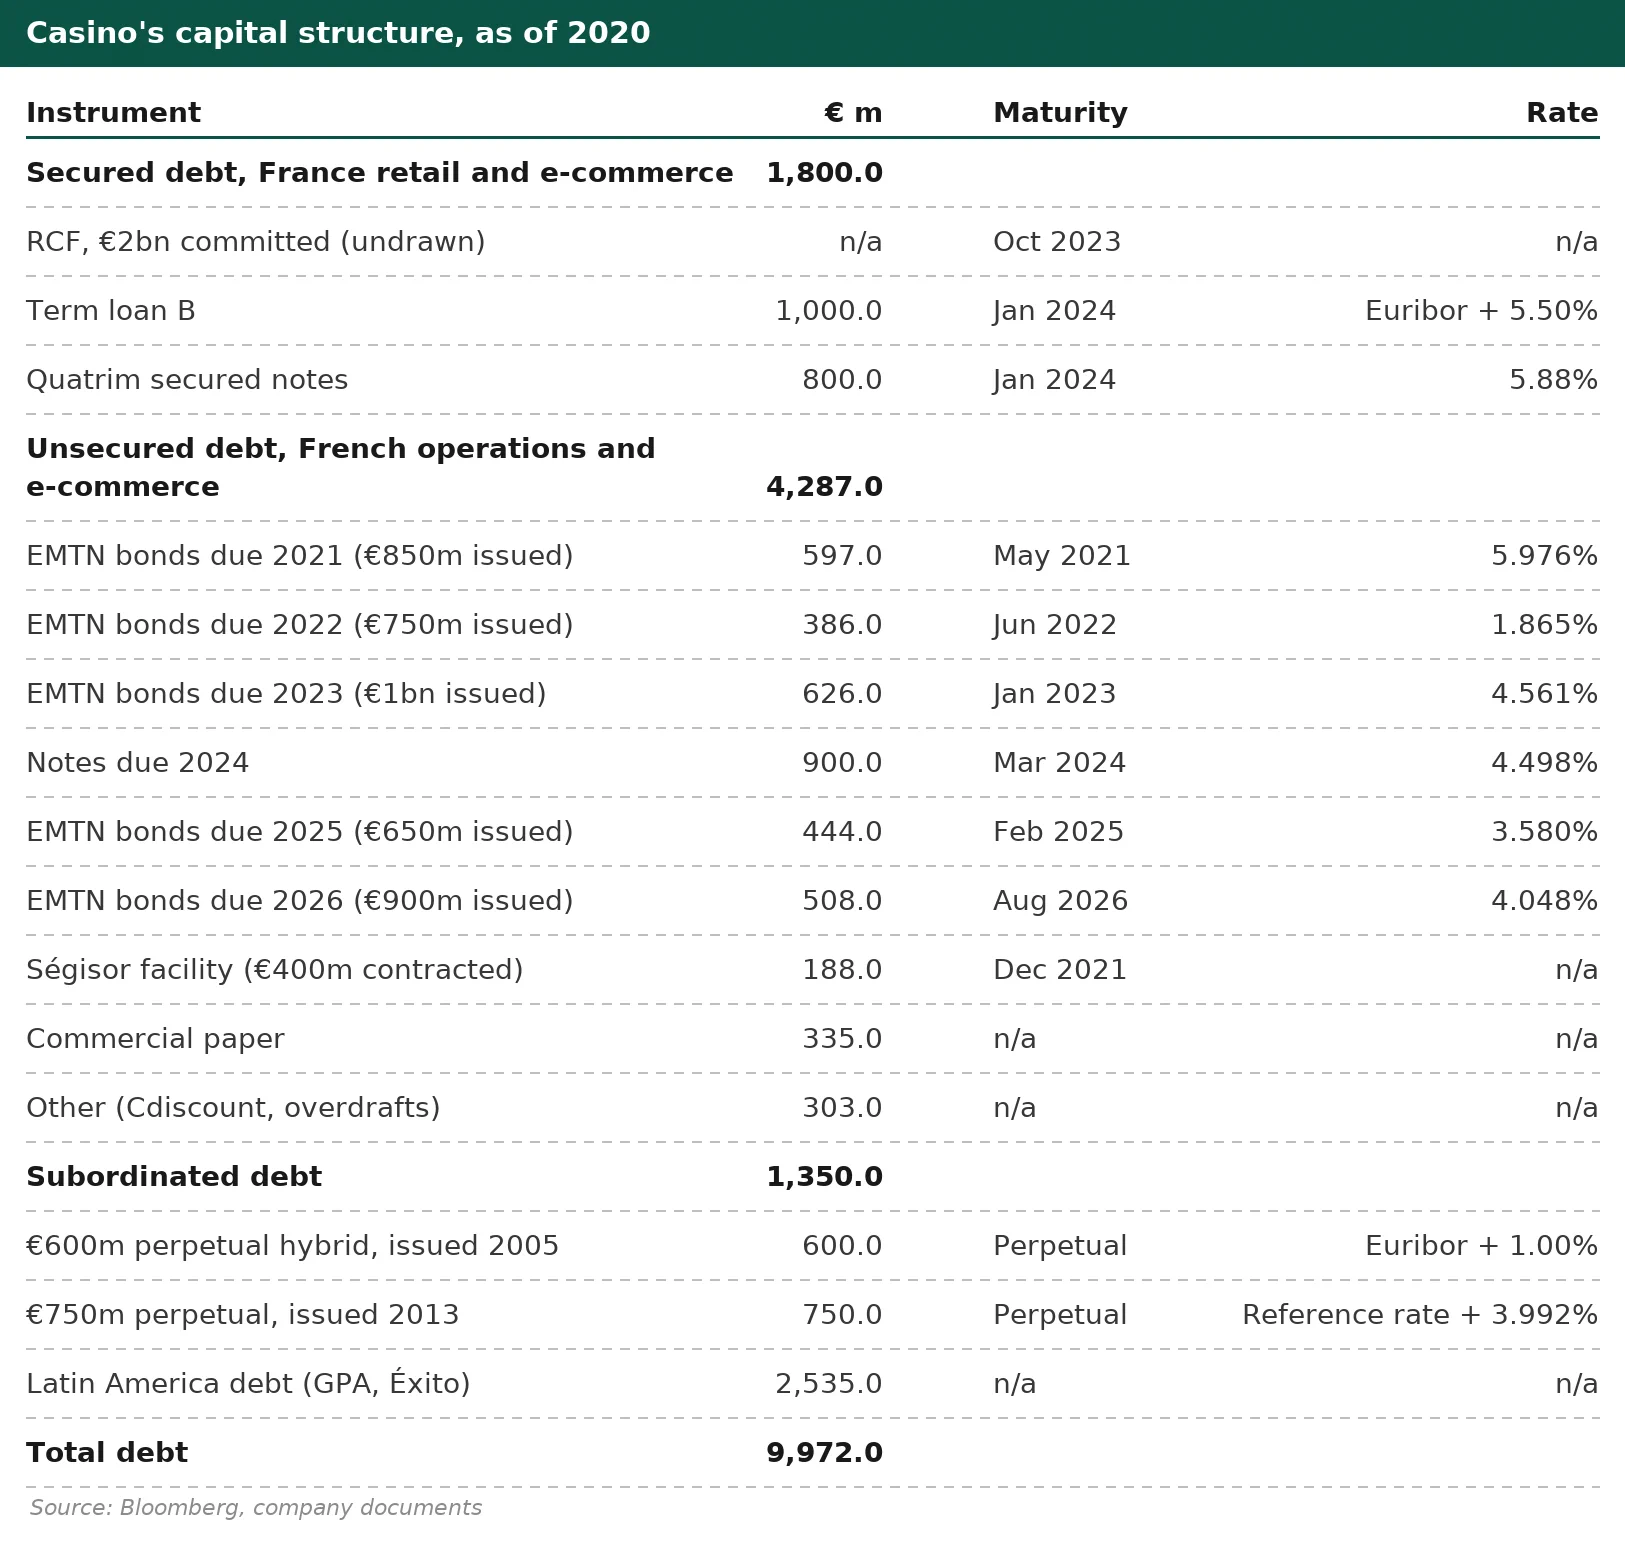
The slide into safeguard: 2019 to 2023
Rallye, whose main asset was its stake in Casino, went into safeguard in May 2019, plagued by not enough sales and too much leverage. The plan the Paris court approved in February 2020 paid Rallye's secured creditors (whose collateral was Casino shares) at least 85% of their claims by the third payment date of the plan, and its unsecured creditors on a ten-year schedule. Casino's own hybrids paid interest only if the group had paid an ordinary dividend in the preceding twelve months. The company itself kept meeting its obligations, helped by the November 2019 refinancing and the March 2021 restructuring described above, but it was managing for liquidity, not performance: disposal proceeds went to creditors, and the French estate kept shrinking while its cost base did not.
By 2022, the broader macro environment (Russia-Ukraine war, rising interest rates, inflation) was impacting companies globally, and Casino was no exception. Higher interest made its floating-rate TLB and the two perps more expensive to carry, and the ongoing disposal proceeds no longer covered its interest bills. The company took more drastic measures, agreeing in 2023 to sell its hypermarkets and supermarkets to Intermarché, Auchan and Carrefour.
Enter Daniel Kretinsky, who had been circling Casino for years. A Czech billionaire who built his fortune buying power plants and industrial assets across central Europe after the fall of the iron curtain, he had a history of acquiring distressed assets: stakes in Sainsbury's and Royal Mail in the UK and a share of the Le Monde newspaper group in France, among other things. His investment vehicle Vesa first disclosed a 4.6% stake in Casino equity in September 2019, then went on to back Rallye's own restructuring with up to €233m through his EP Investment vehicle in early 2020, and lifted his Casino holding to nearly 7% that March.
By the spring of 2023 Kretinsky had built an 11.7% stake and came in as the buyer of control. Alongside him was Fimalac, the investment holding of the French financier Marc Ladreit de Lacharrière, best known as the longtime controlling shareholder of Fitch Ratings and by then Casino's second-largest shareholder. Also joining them was the hedge fund Attestor.
Casino was officially in crisis—it had ~€3bn of maturities looming over the next two years, led by the €2bn RCF due October 2023 and the TLB / Quatrim €800m 5.875% secured notes both due January 2024. The group could neither repay nor refinance them. The unsecured bond market had been largely shut to Casino for years, asset sales were agreed but not yet closed, and any share sales would be prohibitively dilutive if even possible. Casino had asked its creditors in April 2023 to consent to a conciliation without triggering a default under its debt, and the Paris commercial court opened the proceedings on 25 May 2023. Through the conciliation the group preserved liquidity with an agreement with the French state to defer about €300m of tax and social security charges due May to September 2023, in exchange for first-rank pledges, while the conciliators sought covenant waivers and standstills from financial creditors. A lock-up with the Kretinsky consortium followed in July 2023. The Paris court subsequently opened an accelerated safeguard on 25 October 2023.
The 2024 plan: €4.9bn of debt equitized

The end result was a €1.2bn capital increase, €925m reserved to Kretinsky's France Retail Holdings (consortium of Kretinsky, Fimalac and Attestor) at €0.0435 a share, plus new shares issued to the unsecured creditors, whose shares carry warrants struck at €0.1688. Most of the group's secured and unsecured debt, and the TSSDI undated deeply subordinated notes, converted into equity: €4.9bn of principal in the plan, €5.2bn of principal and interest on the final tally (€3.8bn excluding TSSDIs). The consortium ended up with 53.7%; existing shareholders, as a group, went to about 0.3% (a holder of 1% went to 0.003% on a diluted basis, per the company's own note).
What remained was reinstated debt totaling €2.6bn—the €1.4bn TLB, the €711m Monoprix RCF and the Quatrim secured bonds, with Quatrim ring-fenced from the rest of the group. The secured creditors also committed ~€1.2bn of operational financing for two years plus one, and the banks gave an 18-month covenant holiday running to September 2025. Secured debt stopped bearing interest from the date of the approval judgments.
The shareholder class approved the plan because the fairness report put the value of 100 existing shares at zero pre-plan and about €5 after. JCN and the entire board resigned at completion on 27 March 2024. The accounts then booked €3.5bn of non-recurring financial income from the restructuring, the accounting recognition of the discount creditors granted.
The vote: everyone said yes, even the shareholders
The class votes closed on 12 January 2024. Sixteen of the seventeen subsidiary classes approved by the required two-thirds. At the parent, shareholders voted 98.87% in favour and the TSSDI holders 75.62%. GPA, the sole creditor of its class under a guarantee, abstained, and GreenYellow Holding, the sole creditor of one Casino Participations France class, voted against; the inter-class forced application (cram-down) covered the dissent, and the company said it had no impact on implementation. The court approved the plans on 26 February 2024.
Performance still hasn't recovered
Of the three reinstated debts, the TLB is the one that matters now: due March 2027 with a 9% fixed coupon, which means interest for Casino of ~€125m a year by our math.
And cash flow has remained the key challenge here. Despite like-for-like sales turning positive for the first time since the restructuring and adjusted EBITDA rising from €576m to €655m in 2025, free cash flow before financial expenses was still negative every period (-€639m in 2024, -€120m in 2025, -€30m in H1 2026, and -€132m in H1 2026 after financial expenses), so net debt has actually risen: €1.0bn at June 2024, €1.2bn at December 2024, €1.49bn at December 2025, €1.7bn at June 2026. Liquidity went the other way: €1.5bn at the end of 2024 to €1bn at the end of 2025 to €713m at June 2026, with management projecting a floor of €0.5bn through Q3, factoring included.
The covenant holiday ended in September 2025. The group was compliant at 4.66x net leverage (defined as EBITDA after lease payments) against a 7.17x limit at December 2025, at 5.98x against 7.41x at March 2026, and at 6.47x against 6.88x at June 2026, but expects to breach the 6.11x step-down at end-September 2026, for which it will seek waivers. The Quatrim real estate bonds, the one piece the 2024 plan ring-fenced, are being paid down from disposals: ~€140m nominal at December 2025, €109m by May 2026, with the pay-if-you-can coupon cut from 8.5% to 7.5% in April 2025 as the disposal plan ran ahead of schedule. On 13 October Casino extended the bonds' maturity from 15 January 2027 to 15 January 2028, under the option the documentation gives it.
The shares traded at about €0.18 on 16 October 2026, above the €0.1688 warrant strike but not by much.
Round two: FRH's proposal against the TLB lenders

On 24 November 2025 Casino presented its Renouveau 2030 strategic plan, and France Retail Holdings set out its price for supporting it: €910m of new capital, €300m of it cash backstopped by FRH and €610m from converting TLB debt, with the TLB reinstated at €800m for five years at 6% PIK for two years then 6% pay-if-you-can. If nobody else subscribed, FRH would own 68%. The company's own cleansing presentation notes both sides' proposals imply an equity value close to zero pre-transaction, and that the FRH version prices the TLB conversion at 4.3x the new-money subscription price.
The TLB lenders organised fast. A steering committee holding 80% of the TLB (about 96% with other creditors) answered on 3 December 2025. The committee's majority is made up of Attestor, Monarch, Davidson Kempner, Farallon and King Street, with the first four of those publicly named as holding 96% of the TLB debt between them. The lenders put in a proposal of their own on 12 and 19 January 2026: a €1,210m recapitalization, a €910m rights issue open to existing shareholders plus €300m reserved to the TLB lenders backstopped in cash, the TLB cut to €500m with a 3-year maturity and 2-year extension, 9% PIK for two years then 7.5% pay-if-you-can, and materially more deleveraging. Any cash raised above the €300m liquidity tranche repays the TLB at par. In effect, the lenders convert €1.36bn of claims (per the company's cleansing presentation of 6 July 2026) and take the company, with the sponsor left close to nothing.
The standstills continued through the winter and spring. On 6 July 2026 the group announced two firm proposals, and the board, on the ad hoc committee's recommendation, decided on 10 July that absent a consensus the shareholder's proposal best served Casino's corporate interests, subject to two conditions: the TLB lenders get the banks' security package, and the banks waive the two-thirds TLB majority condition for amending the plan. The banks' credit committees agreed in principle on 21-23 July. The TLB lenders refused to extend their consent past 26 July.
The TLB lenders go to court
Conciliation agreements with the banks were signed and filed on 5 August 2026. The next day, the TLB lenders filed at the Paris economic court (seeking termination of the 26 February 2024 plan, on the basis in particular of the event of default the financing documentation attaches to the group entering discussions with its creditors). The same talks the board says it must run are, on the TLB lenders' reading, a default.
The first round went to the company. On 17 August 2026 the judge overseeing the safeguard declared the TLB lenders' claims about the constitution of the new classes inadmissible and dismissed them; the TLB lenders appealed on 24 August. The Paris economic court will rule concurrently on the termination action, the draft plan amendments, and the conciliation agreements.
Two of the three creditor groups have settled in principle. On 21 September Casino announced an agreement with Quatrim bondholders holding about 35% of the Quatrim debt: the Monoprix guarantee is reduced by €10m at realization and extended a year to January 2029, and Ségisor's guarantee is released. On 30 September the RCF, operational financing and Quatrim consents were extended to 31 October 2026, with an option to 15 November if a binding Quatrim agreement is signed by 31 October, and the consents include a standstill on rights arising from the unpaid TLB coupon. The TLB lenders are not part of that extension; their own consents, set to expire at the end of May 2026, were never renewed. Casino had already decided on 24 September not to pay the €65m TLB coupon due 27 September, parking it in a dedicated account pending the proceedings.
Since then the opposing sides have moved closer to a deal than at any point in the dispute. Les Échos reported on 15 October that the broad terms of an agreement between FRH and the TLB lenders are now laid out, though not finalised, with gross debt coming back to about €800m, more than €600m of it taken out through a capital increase backed by Kretinsky; the following day a wire report said Kretinsky was close to a definitive agreement under which he would buy back the lenders' roughly 30% stake. Nothing is signed and the company has not confirmed it; if the outline holds, the fight over who owns the equity ends without a court ruling.
What comes next
- The court calendar: the amendment proceedings and the termination action are to be heard together at the Paris economic court; no hearing date has been made public as of 16 October
- The deadline: Casino targets implementation by the end of H2 2026, and says any amendment would be “massively dilutive for the current shareholders”
- The covenant: the 6.11x breach at end-September needs waivers; the group will ask not to see the default used against it
- The maturity: €1.4bn of TLB, March 2027. Even FRH's proposal leaves a TLB in place; the fight is over its size and who owns the equity
- Quatrim: a binding agreement is targeted by 31 October 2026; the bonds' maturity now runs to 15 January 2028
- Where it trades: the Quatrim bonds were quoted around 97c; the TLB is trading around 58c
- US effect: the 2024 plans were recognized in a chapter 15 in SDNY (No. 24-10252, filed 15 February 2024): a recognition proceeding to give US effect to the French safeguard plans, with the French proceeding treated as a foreign main proceeding (chapter 15 petition, Doc 1). The case closed on 5 June 2024, after implementation. Plan amendments are not addressed in what the docket shows: with the case closed, giving US effect to an amended plan would run through a fresh chapter 15 petition, and we have not seen one filed [our read]
- Governance: Attestor is out of FRH. Its vehicle Trinity transferred its 7.65% stake in France Retail Holdings to EP Equity Investment III on 11 February 2025, under the share purchase agreement of 19 November 2024, and left the consortium's shareholders' agreement and acting-in-concert position. Trinity still holds 10.05% of Casino directly
Sources
- Casino Group, H1 2026 Financial Data Estimates, 30 July 2026 (GlobeNewswire, PDF)
- Casino Group, Status update on the project to adapt and strengthen the financial structure, 28 August 2026 (17 August orders, appeal)
- Casino Group, Status update, Quatrim bonds, 21 September 2026 (35% agreement in principle)
- Casino Group Communication, 24 September 2026 (€65m coupon parked)
- Casino Group, Extension of consents, 30 September 2026
- Casino Group Communication, 23 July 2026 (banks' agreement in principle; conditions)
- Casino Group Communication, 27 July 2026 (consents to 24 September)
- Casino, Cleansing presentation, 10 February 2026 (both proposals)
- Casino, 2025 Financial Data Estimates, 30 March 2026
- Casino Group, 2024 Full-Year Results, 28 February 2025
- Casino, Q1 2024 press release, 24 April 2024 (€2.6bn reinstated; share counts; net debt)
- Casino Group, Capital transactions release, 25 March 2024 (reserved increases; warrants; subscription price)
- Casino, Lock-up agreement presentation, 4 October 2023 (operational financing; Quatrim coupon; covenant holiday)
- Classes vote results, 12 January 2024
- Reuters, 3 January 2024 (53.7%; Sorgem: EV €3.71bn vs net debt €7.88bn; dilution)
- Reuters, 26 February 2024 (court approval; €6.1bn reduction; completion expected 27 March)
- IFR, EMEA Restructuring of the Year (the €8.2bn deal; Attestor's July 2023 switch)
- Challenges, 6 July 2026 (two offers; creditor conversion €1.36bn)
- Le Journal des Entreprises, 6 July 2026 (FRH at 66.8%; €1.4bn due March 2027)
- 9fin, 14 July 2026, banks weigh siding with Kretinsky as TLBs consider a challenge
- Investing.com, FY2025 earnings call transcript, April 2026 (Quatrim coupon cut to 7.5%; disposals ahead of schedule)
- In re Casino, Guichard-Perrachon S.A. and Alexis Ravalais, No. 24-10252 (Bankr. S.D.N.Y., filed 15 February 2024), CourtListener docket 68255707; recognition order 14 March 2024 per secondary coverage; the docket records the case as terminated on 5 June 2024; chapter 15 petition, Doc 1
- Wikipedia, Groupe Casino (background: store disposals to Intermarché, Auchan and Carrefour)
- Casino Group Communication, 13 October 2026 (Quatrim bonds maturity extended from 15 January 2027 to 15 January 2028)
- Groupe Casino, 2019 annual financial report (released 27 March 2020), notes 2, 11.2.4 and 11.5.4 (November 2019 refinancing: €1.0bn TLB at Euribor plus 5.5% and €800m Quatrim 5.875% secured notes, both due January 2024; use of proceeds; no term loan in the 2018 comparative)
- Casino Group press release, 22 October 2019 (refinancing plan announced; completed 21 November 2019)
- Casino Group press release, 16 December 2020 (success of the €400m 6.625% unsecured bond due January 2026, the first unsecured issuance since January 2018, and the €225m TLB tap)
- Groupe Casino, annual financial report 2021 (released 22 March 2022), notes 2, 11.2.3 and 11.2.4 (March 2021 refinancing: €1.225bn 2024 TLB redeemed at 101; new €1bn TLB due August 2025 at Euribor plus 4.0%; November 2021 tap of €425m to €1,425m; €525m 5.25% notes due April 2027; bond issue dates for the 2013, 2014, 2017 and 2018 EMTN tranches)
- Casino Group press release, 11 February 2025 (completion of the transfer by Trinity of its 7.65% stake in France Retail Holdings to EP Equity Investment III, under the 19 November 2024 share purchase agreement; Trinity and Attestor ceased acting in concert; Thomas Doerane resigned as board observer; Trinity holds 10.05% of Casino directly; FRH stake unchanged at 53.04%)
- Casino cleansing presentation, 5 March 2026 (TLB SteerCo initial proposal elements of 24 February 2026: consensual structure with €300m rights issue backstopped by FRH; TLB 6% PIK then 6% pay-if-you-can; FRH-led alternative at 50.1%/49.9%)
- Casino cleansing presentation, 16 March 2026 (revised lender-led proposal of 8 March 2026: full conversion of the TLB into equity, €1,410m rights issue with preferential subscription rights backstopped by TLB debt conversion, new SteerCo-guaranteed RCF)
- Casino Group status update, 31 March 2026 (consents and the maturity of the operational financings extended to end-May 2026; key terms of the new proposals published in a presentation the same day; no agreement yet with FRH or the creditors)
- Casino cleansing presentation, 6 July 2026 (the two firm proposals received 30 June 2026: FRH terms — €1,160m of capital increases of which €495m cash, €725m TLB reinstated rising to €800m with 30% consent, five years, 6% cash or 7% PIK then 6% cash plus 2-3% PIK, FRH c.66.8%; TLB SteerCo terms — €1,760m of which €400m cash, full TLB conversion less €50m reinstated, three years, 9% PIK, lenders c.99.9%; banking partners' in-principle agreement on the €601m RCF, €175m GAPD and c.€740m operational financings)
- Les Échos, 15 October 2026, Julia Lemarchand and Sharon Wajsbrot, “Dette de Casino : Kretinsky planche avec les créanciers sur leur sortie du capital” (the broad terms of an agreement between FRH and the TLB lenders are laid out, not finalised; the aim of bringing gross debt back to about €800m, more than €600m of it crushed via a capital increase backed by Kretinsky)
- Rallye, Document d'enregistrement universel 2019 (deposited with the AMF on 29 April 2020), management report (the February 2020 safeguard plan repayment schedules; the second-rank pledge over about 44 million Casino shares) and note 13.5 (Casino's 600,000 TSSDIs of €600m issued in early 2005, remuneration subordinate to payment of a dividend on ordinary shares in the preceding twelve months, ten-year CMS plus 100bp capped at 9%)
- BFM Business, Matthieu Pechberty, 12 December 2025, “Daniel Kretinsky peut-il être éjecté de Casino par ses créanciers anglo-saxons?” (the principal TLB creditors are the Anglo-Saxon funds Attestor, Monarch, Davidson Kempner and Farallon, holding 96% of the debt)
- Wikipedia, Jean-Charles Naouri (biographical details: born in Bône, Algeria in 1949; first prizes at the national concours général at 14; baccalauréat at 15; first in France in the 1967 entrance examination to the École normale supérieure in mathematics; ENA 1974-76; Treasury auditor and chief of staff to Pierre Bérégovoy; Rothschild & Cie Banque 1987)
- Libération, Christophe Alix, 24 May 2019, “Casino : comment Naouri a joué et perdu avec son empire” (Euris's 1991 rescue of Rallye; the cascade of holdings; the May 2019 sauvegarde)
- JDD, 20 June 2023, “Comment le groupe Casino s'est effondré ces dernières années” (the holding pyramid: Rallye 52.3% of Casino via Euris and Finatis; market share from 11% to under 6% by May 2023 against Leclerc at 23.1%; the descent beginning in 2015)
- Capital, 8 December 2023, “Casino : les raisons de la chute d'une icône de la distribution française” (market share 11% to under 6% in five years; prices up to 30% above Leclerc)
- La Dépêche, 27 May 2023, “Le groupe Casino au bord de la faillite” (external growth funded with debt under Naouri; disposals from 2014, Thailand in 2016, the 2019 sale of 26 hypermarket and 67 Monoprix premises)
- Groupe Casino, annual financial report 2019 (key consolidated figures: net sales €34,645m for continuing operations; group-share net loss of €1,432m, of which €1,048m on discontinued activities, Via Varejo sold 14 June 2019 and Leader Price classified as discontinued)
- Groupe Casino, Group history (October 1992: Rallye brought all of its distribution and restaurant activities to Casino Group, a network of 49 Hyper Rallye hypermarkets, 232 Rallye Super supermarkets, 29 Auto-Service, 70 Marest cafeterias and 6 warehouses)
- ESM Magazine on Kantar Worldpanel data, French grocery market shares (Leclerc about 23-24%, Carrefour about 20%, Intermarché 16-17%, Auchan about 9%, Lidl 8%)
- UFC-Que Choisir, price survey of the eight main banners, September 2021 (Casino the most expensive of the eight; a 98-product basket €348 at Leclerc)
- Capital, 3 March 2022, reporting the UFC-Que Choisir ranking (Casino €408 for the 98-product basket, Carrefour €372, Auchan €381, Leclerc €348)
- Financial Times, September 2019 (Vesa's first disclosed 4.6% Casino stake, amid the restructuring)
- Reuters, 4 March 2020 (Vesa at 6.88% of the capital and 5.17% of voting rights; up to €233m through EP Investment to refund Rallye derivatives deals)
- The Telegraph, 5 July 2023 (the Czech Sphinx nickname; fortune from Czech power plants after the fall of the iron curtain; Sainsbury's and Royal Mail stakes)
- Sky News, 16 December 2024 (biography: the 2018 Le Monde stake)
- Chain Reaction Research, GPA's (Casino Group) beef supply chain (FY2018: GPA about 31% of Casino net revenues and 39% of EBITDA)
- Casino Guichard-Perrachon capital structure snapshot, Capital IQ, 30 September 2020 (snapshot provided by the author)
- Bloomberg, Angelina Rascouet and Irene Garcia Perez, 26 May 2023, “Casino to Talk With Creditors as Conciliation Process Starts” (court-supervised talks beginning, the conciliation to last up to five months; shares, suspended since before the market opened on 23 May, down 8.2% to €6.205; notes due March 2024 indicated at 21 cents on the euro)
- Reuters, Dominique Vidalon and Chiara Elisei, 26 May 2023, “Retailer Casino enters court-backed talks with creditors” (the Paris Commercial Court opened a conciliation for an initial four months, extendable by one; Casino had asked creditors in April 2023 to consent to the opening without triggering a default under its debt; creditors included BNP Paribas, Crédit Agricole and international hedge funds)
- Casino Group press release, 21 June 2023, Update on the conciliation proceedings (conciliation opened 25 May 2023, running to 25 September and extendable to 25 October; agreement in principle with the French state to defer circa €300m of tax and social security liabilities due May-September 2023, against first-rank pledges; the conciliators to seek waivers of the 30 June and 30 September 2023 RCF covenants and standstills from financial creditors)
- Reuters, Dominique Vidalon and Helen Reid, 28 July 2023, “Casino clinches debt deal led by Czech billionaire Kretinsky” (the consortium led by Kretinsky's EPGC alongside Casino's biggest creditor Attestor and second-biggest shareholder Fimalac; the €1.2bn of new equity of which €925m reserved to the consortium)